

Money App - Cash Advance

- 2.44K Reviews
- 4.2
- Downloads
- 500,000+
Our take on Money App - Cash Advance from Appgk
Money App - Cash Advance is a finance app from PRG Ventures that caught my attention because it focuses on a very specific problem: finding emergency cash when an ordinary payday does not stretch far enough. I approached it less like a general budgeting tool and more like a possible short-term option for an unexpected bill, a gap between paychecks, or a necessary purchase that cannot wait.
My overall impression is mixed in a useful way. The app is free to install, has an Everyone age rating, and works on Android devices running version 7.0 or later. That makes it accessible to a broad audience. At the same time, an app in this category deserves more caution than a casual utility. The important question is not simply whether it opens or looks straightforward, but whether the process suits your situation and whether you understand the repayment implications before accepting anything.
Where the experience can become confusing
The first point I would clarify is that installing a cash advance app is not the same as receiving money. The app can provide a route to request emergency funds, but approval, eligibility, timing, and the final terms are separate matters. I would not download it while assuming that an advance is guaranteed just because the app is available at no charge.
That distinction matters in a stressful moment. If a utility payment, medical expense, or transport problem is already urgent, users often rush through screens and focus only on the amount they hope to receive. My advice is to slow down at every stage where the app presents financial information. Read the repayment details, check the total cost, and make sure the expected repayment date fits your real income rather than your best-case estimate.
Best Parts of Money App - Cash Advance
Things to Keep in Mind About Money App - Cash Advance
Another common source of friction is expecting the app to behave like a traditional bank. A banking app usually shows accounts and transactions that already exist. A cash advance service may instead require an application flow, identity checks, income-related information, or a connection to financial information before it can assess a request. I would treat each requested step as part of an eligibility process, not as a promise that money will arrive immediately.
The most important practical rule is to separate access to the app from access to cash. That simple distinction prevents a lot of disappointment and helps you judge the service on the terms it actually presents.
News and Features Related to Money App - Cash Advance

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The app has built a noticeable audience, with more than half a million installs and an average rating of 4.2 from roughly ten thousand ratings. Those figures suggest that many people find the basic concept useful, but they do not tell me whether the app is right for every financial emergency. A rating can reflect ease of use, successful access, or general satisfaction; it cannot replace reading the offer shown for your own circumstances.
What I would check before starting
I would begin by confirming that the device meets the Android requirement and that the operating system is up to date enough for normal sign-in and security functions. Money App currently appears as version 2.47.0, so keeping the installation current is sensible. Updates can address compatibility problems, but they can also change screen layouts, so I would avoid relying on an old walkthrough if a button appears in a different place.
Don't want to read the full review?
Next, I would prepare the information needed for a careful application rather than trying to complete it while distracted. Use your own device, a stable internet connection, and an email address or phone number that you can access. If the app asks you to connect financial information, check that you are selecting the correct account and that the details are current. A wrong account, an outdated login, or a recently changed password can make a technical problem look like a rejection.
I would also check the basic financial question before entering the request: what exact expense am I covering, and how will the repayment fit into the next pay cycle? For example, if my car needs a necessary repair before work, I would compare the possible advance with the repair cost and then write down the repayment date alongside rent, utilities, and other fixed commitments. That small exercise is more useful than focusing on the maximum amount displayed in the app.
Screenshots
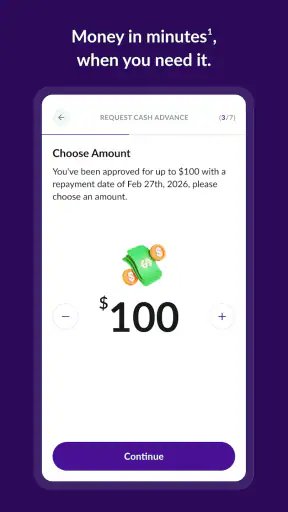
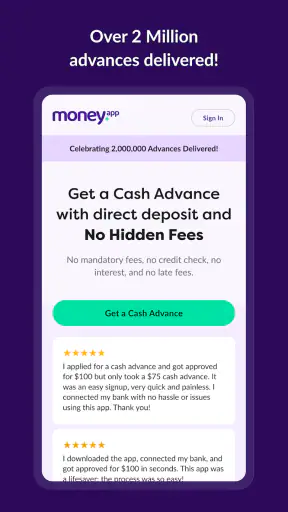
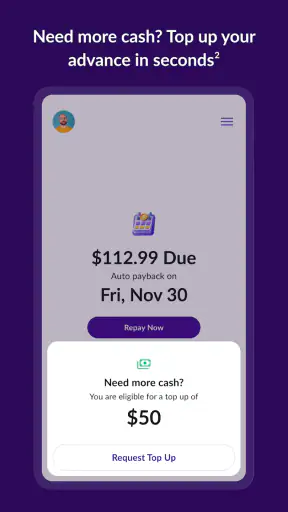
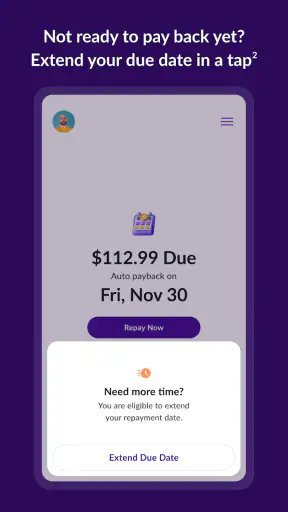
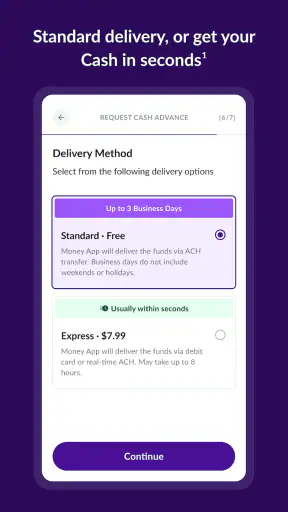
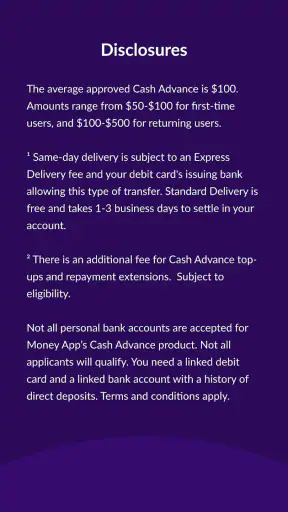
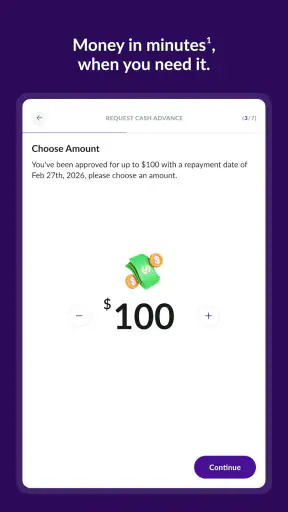
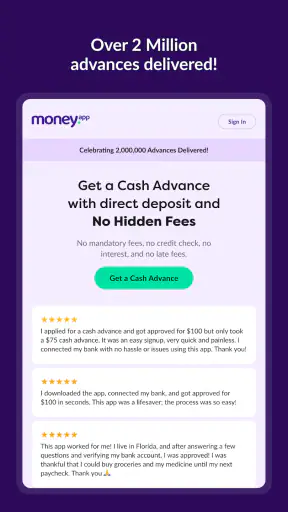
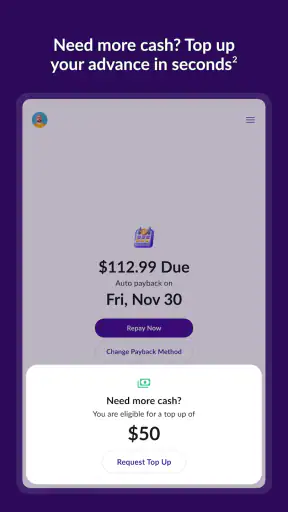
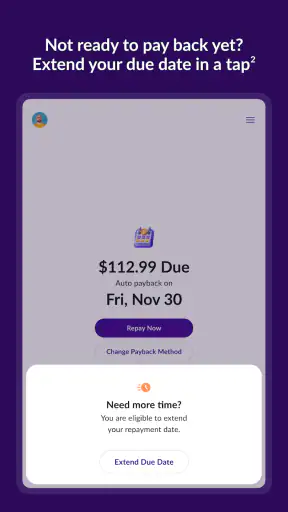
Because the app is free, there is no installation charge to weigh up. That does not mean every possible advance is cost-free. Before accepting an offer, I would look for the total repayment amount, any applicable fee, the scheduled date, and what happens if the repayment cannot be made as planned. If those details are difficult to locate or understand, I would pause instead of treating speed as more important than clarity.
Privacy is another setup check I would not skip. Finance apps handle information that can affect your personal security. I would read the permission prompts and privacy explanations in the app, avoid installing it from an unofficial source, and never share a password or verification code with another person claiming to help. These are ordinary precautions, but they matter more when an app is connected to urgent financial decisions.
A realistic emergency workflow
Imagine that I have an unexpected prescription expense two days before payday. I would first confirm the amount needed and whether a cheaper, non-borrowing solution exists, such as asking the provider about a payment arrangement or checking whether my bank offers an existing overdraft option. If Money App remains under consideration, I would open the app, review the available request path, and enter information slowly.
At the offer stage, I would compare the money received with the total amount repaid. I would then check whether the scheduled withdrawal or repayment date lands before my income arrives. If it does, the advance could create a second problem even if it solves the prescription bill. In that situation, a conversation with the bill provider might be safer than borrowing through the app.
If the timing and cost make sense, I would save a note of the repayment date and amount outside the app. I would not rely only on a notification, because notifications can be disabled, delayed, or overlooked. I would also keep a record of the confirmation screen or email in a secure place, without exposing sensitive information in a screenshot shared with anyone else.
This workflow shows where the app is most useful: as a focused tool for a short, defined gap where the repayment is realistic. It is less suitable as a way to cover recurring shortages. If I needed help every month for groceries, rent, or regular bills, I would see that as a sign to look for a broader solution rather than repeatedly taking advances.
Recovering when the process does not move forward
If the app stalls during setup, I would first close and reopen it, check the connection, and make sure the application is updated through the normal app store. I would avoid repeatedly submitting the same request while a previous attempt may still be processing. Duplicate attempts can make it harder to understand which request is current and may create unnecessary confusion in the account history.
When a linked account is not recognized, I would verify the login details outside the app by signing in directly through the financial institution’s official service, then return to the process. I would not use a link sent by a stranger or disclose credentials through a message. If the account has recently changed, been closed, or has unusual security restrictions, the issue may be with the account connection rather than Money App itself.
For identity or eligibility screens, accuracy matters more than speed. I would check spelling, address details, and dates against official records before trying again. A mismatch can interrupt an automated review. I would also make sure the phone can receive the required verification message and that its date and time settings are correct, since an expired code can look like a failed application.
If the app shows a request as pending, I would avoid assuming that reinstalling will make it faster. Reinstalling may remove local session information but does not necessarily change an external review or transfer process. I would record the status, note when I submitted it, and use the in-app support route if one is available. When contacting support, I would describe the exact screen and error message without sending passwords, full account numbers, or security codes.
A useful recovery habit is to change only one thing at a time. If I switch networks, reset a password, reinstall the app, and submit another request all at once, I lose track of what helped. A slower sequence gives me a clearer answer and reduces the risk of creating multiple incomplete attempts.
When the app is not the cause
Not every failed cash request is a software failure. A bank connection can be unavailable, an account can have a hold, a phone number can be unable to receive messages, or the information entered can fail to match another record. The app may simply be reporting a condition that exists elsewhere.
This is why I would test the surrounding pieces separately. Can I access the relevant bank account through its official app? Is the account active and able to receive or send funds? Is the phone connected to a reliable network? Are there restrictions on the device that block notifications or verification? Answering those questions helps distinguish a genuine app problem from a financial or account issue.
I would also remember that eligibility decisions are not necessarily controlled by the appearance of the interface. A clean screen and a successful login do not guarantee an offer. Conversely, an offer that does appear may still not be a good choice if its repayment creates pressure. The app can make the request process easier to follow, but it cannot remove the underlying risk of short-term borrowing.
Compared with asking a bank for an overdraft, using a credit card, or borrowing from someone close to me, Money App may feel more direct because it is designed around emergency cash rather than everyday account management. However, traditional options can be better when they provide clearer terms, a longer repayment window, or an existing relationship I already understand. A credit union or employer-based option may also be more appropriate for a larger need, while a bill negotiation is often better when the problem is a single due date rather than a lack of income.
The app is also not a replacement for a budgeting application. A budget can help identify recurring leaks, plan bills, and build a reserve; a cash advance addresses an immediate gap. Using the latter to solve the former can create a cycle in which each paycheck is partly committed before it arrives. I would use Money App only after deciding that the expense is genuinely time-sensitive and that repayment is credible.
Who will get the most value from it?
I think the strongest fit is an adult who needs to investigate a modest, short-term cash gap, can provide accurate information, and has a dependable income arriving soon. The Everyone rating makes the app broadly accessible from a content perspective, but financial suitability is different from age suitability. A person should understand the repayment obligation before proceeding, regardless of how simple the interface feels.
It may also suit someone who prefers handling an emergency request digitally rather than making several phone calls. The free installation lowers the barrier to exploring the process, and the app’s finance focus keeps the purpose clear. Still, I would judge it by the terms shown during the request, not by the convenience of reaching the first screen.
I would skip it when the amount needed is large, the repayment date is uncertain, or my income is already committed to essential bills. I would also avoid it if I am considering an advance for a recurring expense or to repay another short-term loan. In those cases, a nonprofit financial counselor, a creditor payment arrangement, a bank product with transparent terms, or a longer-term income and expense plan would be a better direction.
Users who dislike sharing financial information with third-party services may also prefer a traditional option they already use. That is not a criticism of this particular app; it is a personal trade-off. Convenience can require more account setup, while familiar financial products may offer a process that feels slower but easier to understand.
My practical verdict after weighing the trade-offs
Money App - Cash Advance is a reasonable app to consider when the need is urgent, narrow, and temporary. PRG Ventures has positioned it in a category where speed and accessibility matter, and its free availability makes it easy to examine without paying to install it. The current version is 2.47.0, and the app has enough adoption to make it a recognizable option rather than an obscure experiment.
My recommendation comes with a firm condition: read the complete offer before accepting anything. Check the amount you receive, the total repayment, the date funds are due, and the consequences of missing that date. Keep your own reminder, protect your login information, and do not submit repeated requests simply because the first one is taking time.
The app is not a magic fix for an unstable budget, and it should not be treated as one. For a one-off emergency that can be repaid without sacrificing essentials, it may be worth exploring. For ongoing financial strain, a different solution is more likely to help. I would describe it to a friend as a potentially useful short-term tool, but only one that deserves the same care I would give any borrowing decision.
Money App - Cash Advance FAQ
What is Money App – Cash Advance, and how does it work?
Money App – Cash Advance is designed to help eligible users request access to a small amount of money before their next payday. After creating an account, you may need to provide personal, employment, income, and banking information so the service can evaluate your request. Approval, available amount, transfer speed, and repayment conditions can vary depending on your profile and the provider’s policies.
Is Money App – Cash Advance a loan, and what fees should I expect?
Users should carefully review the offer before accepting it because a cash advance may involve subscription charges, express-transfer fees, service fees, or other costs. The exact pricing depends on the app, your eligibility, and the selected funding option. It is important to read the agreement, repayment schedule, and total cost rather than assuming that every advance is free.
How quickly can I receive money through the app?
The application may display an estimated delivery time after your request is approved, but funding is not always immediate. Standard transfers can depend on your bank, weekends, holidays, and processing times, while faster delivery may require an additional fee. Approval does not guarantee instant access, so avoid relying on the service for emergencies until the money has actually arrived.
What information and permissions does Money App – Cash Advance require?
To assess eligibility and connect an account, the app may request details such as your name, contact information, identification, income, employment history, and bank account information. It may also ask for permissions related to notifications or financial-account connectivity. Before continuing, check the privacy policy, understand how information is shared and stored, and grant only permissions you consider necessary.
Who can use Money App – Cash Advance, and are there repayment risks?
Eligibility requirements may include being an adult resident of a supported location, having a valid bank account, receiving regular income, and meeting identity or verification checks. Requirements can change and approval is not guaranteed. Repayment is usually scheduled automatically or according to the agreement, so users should confirm the withdrawal date and maintain enough funds to avoid failed payments, fees, or other financial consequences.











